


What Does It Really Cost to Start an Independent Estate Agency in London?
The dream of opening a property business of your own is still alive. But in 2026, launching an independent estate agency in London takes more than a smart shopfront, a decent suit and a subscription to Rightmove. Here’s what aspiring agency owners should realistically budget.
- The short answer: around £50,000 to £150,000
- 1. Company formation: surprisingly cheap
- 2. Compliance: the bill nobody sees coming
- 3. Professional indemnity insurance
- 4. The London office: where the numbers get serious
- 5. The portals: the elephant in the room
- 6. Your CRM and technology stack
- 7. Branding and website
- 8. Staff: the real recurring expense
There is something deeply attractive about the idea of an independent estate agency.
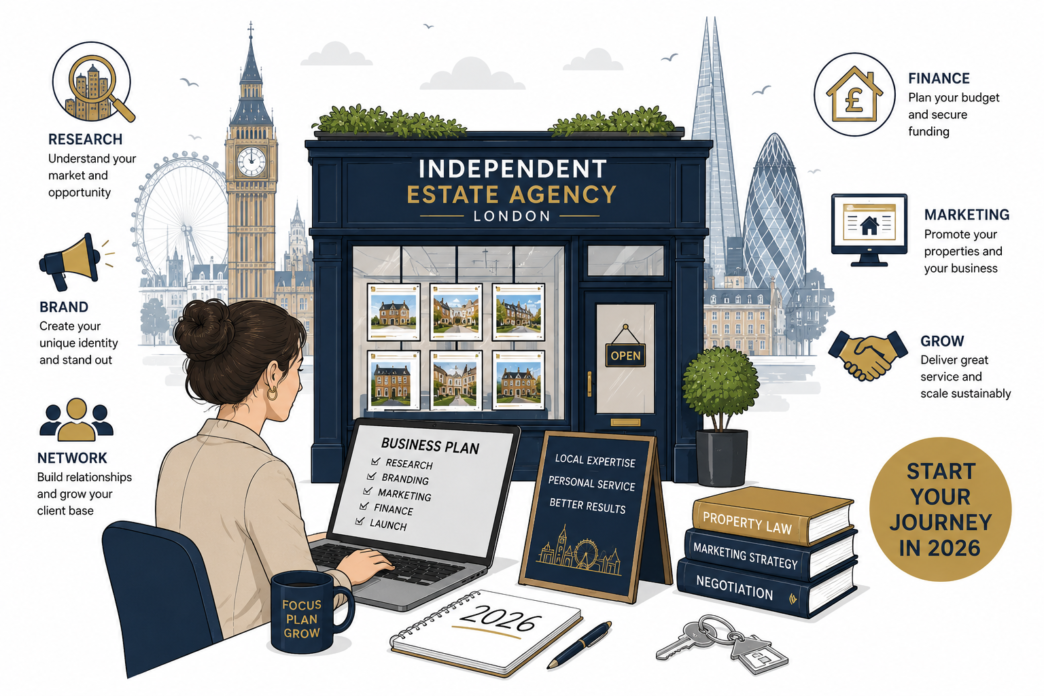
You know your patch. You know the streets, the schools, the buyers, the landlords and — perhaps most importantly — the weaknesses of the big corporate agents. You imagine a smaller, sharper business: fewer layers, better service, local expertise and a brand people actually remember. 
The good news is that technology has made it possible to start an estate agency with considerably less capital than was required a generation ago.
The bad news? London remains London.
Property portals, premises, salaries, professional insurance, compliance, marketing and the simple cost of surviving until your first commissions arrive can turn a seemingly inexpensive start-up into a six-figure proposition surprisingly quickly.
So, what should you actually budget?
The short answer: around £50,000 to £150,000
For a genuinely lean, owner-operated agency, it is possible to launch for around £30,000–£50,000 if you work from a small office or serviced workspace, keep staffing extremely tight and avoid expensive fit-outs.
A more credible budget for a professional single-branch London agency is £75,000–£150,000.
And if you want a prominent high-street office, several employees, substantial portal exposure and enough cash to survive a slow first year, £150,000–£250,000+is entirely plausible.
The critical point is that launch cost and cash required are not the same thing.
You might be able to open the doors for £50,000. That doesn’t mean £50,000 is enough capital to run the business.
Estate agency is particularly unforgiving because revenue is lumpy. You can spend weeks generating instructions, months progressing transactions and then discover that a sale falls through just before completion — taking your anticipated commission with it.
The sensible entrepreneur therefore budgets for working capital first and fancy furniture second.
1. Company formation: surprisingly cheap
The formal cost of establishing a limited company is one of the least frightening parts of the exercise.
As of 2026, online incorporation with Companies House costs £100, while the digital confirmation statement fee is £50.
But don’t mistake the £100 Companies House fee for the cost of establishing a properly structured business.
You’ll probably want an accountant, legal advice, appropriate contracts and terms of business, employment documentation if you’re hiring, and potentially advice on the structure of the company.
Realistic initial budget: £500–£2,500.
2. Compliance: the bill nobody sees coming
Estate agency is a regulated business, and compliance is not an optional extra.
An estate agency business generally needs to register with HMRC for anti-money-laundering supervision before conducting relevant estate agency activity. HMRC states that trading without the required registration is a criminal offence.
The current HMRC fee structure includes a £300 application fee, £400 per premises, and an annual £400 premises fee, with a £40 approval-check fee applying to relevant beneficial owners, officers or managers.
Then there is the practical side: your AML risk assessment, policies, customer due diligence procedures, staff training, record-keeping and ongoing compliance.
You will also need to consider data protection. The ICO explicitly confirms that estate agencies need to pay a data protection fee, with the amount depending on the organisation and applicable tier; current fees range from £52 to £3,763.
And if you are selling residential property, you’ll need membership of an approved redress scheme. The Property Ombudsman, for example, currently lists a first-time joining fee of £74.26 plus VAT and an annual fee of £277.96 plus VAT per branch for its relevant registration/membership categories.
Allow roughly £1,000–£3,000 initially for statutory and compliance-related costs, and considerably more if you outsource compliance work or require specialist legal advice.
3. Professional indemnity insurance
This is another area where the cheapest quote isn’t necessarily the best quote.
An estate agency handles valuable transactions, confidential information and potentially contentious advice. Professional indemnity insurance is therefore an important part of the risk-management structure — and is also relevant when joining certain industry organisations.
Add public liability, employers’ liability if you employ staff, contents cover, cyber insurance and potentially legal-expenses cover, and the insurance package starts to look rather different.
Budget: £1,500–£4,000 a year for a small agency, depending heavily on turnover, staffing, services and cover.
4. The London office: where the numbers get serious
This is perhaps the biggest lifestyle-versus-business decision you’ll make.
Do you really need a traditional high-street office?
Twenty years ago, the answer would have been almost certainly yes. In 2026, the answer is much less obvious.
A serviced office or flexible workspace can give a new agency a prestigious address, meeting rooms and professional infrastructure without committing to a long commercial lease and a substantial fit-out.
London’s flexible-office market remains strong in 2026, with demand concentrated on good-quality, well-connected buildings.
At the other end of the spectrum, prime conventional London office space can be extraordinarily expensive. Q1 2026 research put prime City rents at about £130.80 per sq ft, with Mayfair and St James’s reaching around £201 per sq ft.
Of course, an independent agency doesn’t need Mayfair rent.
A modest suburban office, particularly outside prime central locations, can be dramatically cheaper.
But rent isn’t the whole equation. You’ll need to consider:
- Business rates
- Service charges
- Deposit
- Legal fees
- Fit-out
- Furniture
- Signage
- Utilities
- Internet
- Alarm/security
- Cleaning
- Insurance
Lean option: £500–£2,000 a month for flexible/serviced accommodation.
Small conventional office: potentially £2,000–£5,000+ a month once the wider occupancy cost is considered.
High-street/prime location: potentially much more.
And don’t forget the opportunity cost. Every £1,000 spent on rent is £1,000 that isn’t sitting in your working-capital account.
5. The portals: the elephant in the room
This is where the independent estate agency business model becomes interesting.
You can build a website for relatively little money.
You can buy laptops cheaply.
You can rent a desk.
But if your business depends upon residential sales and you want meaningful exposure to London’s online property audience, property portals can become one of your largest operating expenses.
The major portals generally don’t offer simple, universally applicable public price lists. Costs depend on location, stock, contract and package.
That makes it difficult to put a definitive number on portal expenditure.
As a broad planning assumption, however, a new agency should think in terms of several thousand pounds a month rather than several hundred once its complete marketing and portal strategy is established.
And this is why your business model matters.
An agent targeting £500,000 family homes in outer London has a very different portal economics problem from an agent selling £2 million houses in southwest London.
If your average completed fee is £8,000, spending £4,000 a month on lead generation may be perfectly rational.
If your average fee is £2,500, it could be disastrous.
Never build the business plan around portal expenditure alone. Build it around cost per instruction and cost per completed transaction.
6. Your CRM and technology stack
The modern estate agency office can be remarkably small because so much of the traditional infrastructure has moved into the cloud.
A CRM can manage applicants, properties, enquiries, viewings, offers, chains, marketing and compliance. Some platforms also integrate with portals and other services.
Pricing varies enormously. Current industry comparisons put entry-level and independent-agency CRM costs anywhere from roughly £100–£500+ a month, depending on the platform and configuration, with larger systems costing substantially more.
Then add:
- Telephony
- Microsoft 365 or Google Workspace
- Website hosting
- E-signatures
- AML/ID verification
- Digital marketing
- Accounting software
- Cybersecurity
- Cloud storage
- Photography
- Floor plans
- Virtual tours where appropriate
Realistic technology budget: £500–£1,500 a month for a small agency, before the major property portals.
The temptation is to buy everything.
Don’t.
The winning independent agency isn’t necessarily the one with the most technology. It’s the one where technology removes administration and gives the negotiator more time to win instructions.
7. Branding and website
This is an area where independents can genuinely beat the corporates.
A memorable local brand can be worth considerably more than a generic blue-and-white corporate identity.
But there is a difference between cheap and lean.
A £300 website that looks like it was assembled over a weekend can undermine a £1 million listing.
Conversely, you don’t necessarily need a £30,000 website.
For a new agency, I’d budget approximately:
Brand identity: £1,000–£5,000
Website: £2,000–£8,000
Photography/video/launch content: £1,000–£3,000
Signage and printed materials: £1,000–£3,000
Total: £5,000–£15,000.
The objective isn’t to look expensive.
It’s to look credible.
8. Staff: the real recurring expense
Here is where many new agency business plans become dangerously optimistic.
The founder thinks:
“I’ll employ two negotiators once things get busy.”
The problem is that “busy” usually arrives after you’ve already needed the people.
A small London agency might launch with:
Founder + one negotiator + part-time administrator
or even:
Founder + outsourced administration
That can keep the initial payroll manageable.
But once you employ three or four people, salaries, National Insurance, pension contributions, holiday pay, recruitment and training rapidly become a major fixed cost.
As a rough planning figure, a small team of three employees could easily represent £100,000–£150,000+ a year in total employment cost, depending on experience and remuneration.
And London tends to demand experienced people.
A brilliant negotiator can generate substantial revenue.
A mediocre negotiator can simply generate salary expense.
That makes recruitment one of the most consequential investments you’ll make.
So, what does a realistic launch budget look like?
Here’s one way of thinking about it.
| Cost | Lean agency | Comfortable launch |
|---|---|---|
| Company/legal setup | £1,500 | £4,000 |
| Compliance & registrations | £1,500 | £3,000 |
| Insurance | £2,000 | £4,000 |
| Office/deposit/setup | £5,000 | £20,000 |
| Branding & website | £5,000 | £12,000 |
| Furniture & equipment | £3,000 | £8,000 |
| CRM/software | £3,000 | £8,000 |
| Initial marketing | £5,000 | £15,000 |
| Portal/lead-generation setup | £5,000 | £15,000 |
| Recruitment/training | £2,000 | £8,000 |
| Working-capital reserve | £25,000 | £75,000 |
| Approximate total | £58,000 | £172,000 |
These aren’t official industry tariffs; they’re planning estimates designed to illustrate the difference between a highly lean launch and a more fully funded single-branch operation.
And the most important line in that table isn’t the website.
It’s the final one.
The £50,000 mistake
If you’ve got £50,000 in the bank, it’s tempting to think:
“Great. I can afford to start.”
Maybe.
But suppose you spend £15,000 fitting out an office, £8,000 on branding and equipment, £5,000 on initial marketing and £10,000 on deposits, setup and miscellaneous costs.
Suddenly you’ve got £12,000 left.
Then comes payroll.
Rent.
Portal bills.
Insurance.
Software.
Accountancy.
Telephone bills.
Marketing.
And the sale you thought would complete next month gets delayed.
That’s why working capital is arguably more important than startup capital.
A sensible founder should aim to have enough money to keep the business functioning for six months or more without relying on optimistic commission forecasts.
The lean London model
Interestingly, the most compelling new agencies may not resemble the traditional estate agency at all.
Imagine a founder operating from a serviced office.
No expensive high-street frontage.
One excellent negotiator.
One administrator working flexibly.
Professional photography outsourced.
Floor plans outsourced.
Cloud-based CRM.
Digital valuations.
Virtual viewings where appropriate.
A strong local website.
Aggressive but targeted prospecting.
The founder spends their time doing the thing that actually generates revenue:
winning instructions.
That model might get off the ground for £40,000–£70,000, provided the founder has sufficient industry expertise and is prepared to operate very leanly.
It also reduces the agency’s break-even point.
And break-even point is the number that really matters.
The question isn’t “How much does it cost?”
It’s “How many properties do I need to sell?”
Suppose your average completed fee is £6,000.
If your annual fixed and semi-variable costs come to £180,000, you need approximately:
30 completed transactions a year
just to generate £180,000 in gross fee income.
That’s 2.5 completions a month.
Now imagine your average fee is £10,000.
Suddenly the same cost base requires only:
18 completions a year.
That’s why London can be such an attractive market for independents.
You don’t necessarily need enormous transaction volumes if you’re operating in a higher-value segment.
The flip side is that competition is fierce and sellers have plenty of choice.
Your business therefore needs a very clear answer to one question:
Why should a London homeowner instruct you rather than the three agents already competing for their property?
If the answer is simply “we offer great service”, you don’t have an answer yet.
Sales-only or sales and lettings?
This decision can materially alter your capital requirements.
A sales-only agency can potentially operate with a relatively simple infrastructure.
Once you move into lettings and property management, the compliance and operational burden increases.
For example, where a letting or property management agent in England holds client money, membership of an approved Client Money Protection scheme is mandatory. Failure to join can result in a fine of up to £30,000.
There are also additional requirements around client accounts, fee transparency and the handling of landlords’ and tenants’ money.
That doesn’t mean lettings is a bad business.
Far from it.
Recurring management income can be extremely attractive because it creates revenue that isn’t dependent upon completing a sale every few months.
But it should be treated as a different operational proposition — not simply “sales plus a few rentals”.